Hey there, fellow Bay Staters! If you’ve ever found yourself scratching your head and wondering, “Just how much is auto insurance in Massachusetts?” then you’re in the right place. Navigating the world of auto insurance can feel like wading through a sea of confusing jargon and endless options. But don’t worry—we’ve got you covered.
In this guide, we’ll break down everything you need to know about auto insurance in Massachusetts. From understanding the bare minimum coverage required by law to uncovering hidden discounts that could save you a bundle, consider this your ultimate roadmap to getting the best bang for your auto insurance buck.
Understanding Auto Insurance Requirements in Massachusetts
Did you know that driving without insurance in Massachusetts can lead to severe penalties? In fact, Massachusetts has some of the strictest insurance laws in the country.
Here’s the deal: every driver in Massachusetts must carry auto insurance. But what exactly does that mean for you? Let’s break it down.
Minimum Auto Insurance Requirements
In Massachusetts, the state mandates specific types of coverage. You need to have at least $20,000 for bodily injury per person and $40,000 per accident. Plus, there’s the requirement for property damage coverage, which kicks in at $5,000 per accident. But that’s not all. You’ll also need personal injury protection (PIP) of $8,000.
Why all these requirements? Simply put, they ensure that everyone is covered in case of an accident. And they aren’t optional. If you’re caught without these minimums, you’re looking at fines, license suspension, or even jail time. No joke!
Types of Coverage Available
Besides the basics, there are additional coverages you might consider. These include Comprehensive and Collision coverage. Comprehensive handles things like theft or weather damage. Collision covers your car when it’s… well, in a collision. And trust me, if you’re financing your car, lenders often require these.
Another coverage to consider is Uninsured/Underinsured Motorist. This is crucial if you get into an accident with someone who doesn’t have adequate insurance. Massachusetts has more uninsured drivers than you might think. So, it’s a real lifesaver.
Penalties for Not Having Insurance
What happens if you skip out on insurance? The penalties are harsh. You could face fines from $500 to $5,000, and your license could be gone for up to a year. Plus, the costs don’t stop there. Your insurance rates will likely skyrocket once you do get coverage.
Pro Tip: Before hitting the road, double-check that you’re meeting all state insurance requirements. It could save you a ton of headache (and money).
In short, not having the right coverage isn’t just risky—it’s downright costly.
Factors Influencing Auto Insurance Rates in Massachusetts

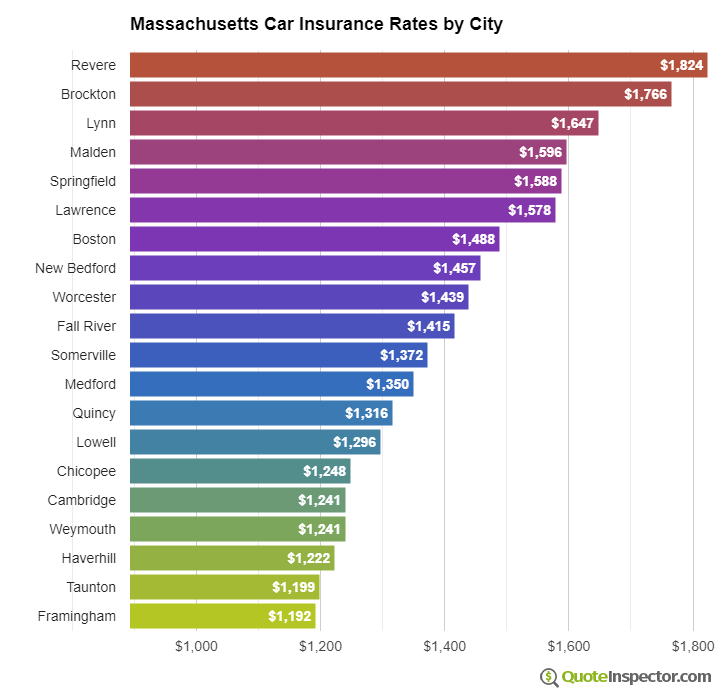
Did you know that where you live in Massachusetts can significantly impact your auto insurance rate? It’s true, and it’s just the tip of the iceberg. Auto insurance rates vary widely due to several factors.
Understanding these factors can help you navigate the complex world of auto insurance pricing in Massachusetts. Let’s break down the primary influencers.
Location, Location, Location
One of the biggest factors affecting your insurance rate is your zip code. You might be thinking, “What does my zip code have to do with anything?” Well, quite a lot! Areas with higher crime rates or a significant number of accidents often see higher insurance premiums.
Living in urban areas like Boston could mean your premiums are higher compared to rural spots such as the Berkshires. Why? More cars and congestion lead to increased risks.
| Region | Average Annual Premium |
|---|---|
| Boston | $1,500 |
| Springfield | $1,250 |
| Berkshires | $1,000 |
Ages and Driving History Matter
If you’re a young driver in Massachusetts, brace yourself for potentially higher rates. Insurers often see younger drivers as higher risk due to their lack of experience.
But here’s the deal: having a clean driving record can lead to significant discounts. No accidents? No tickets? You might save a bundle.
Pro Tip: Maintain a spotless driving record to unlock the best rates possible. Avoiding traffic tickets and accidents is not just good for your safety, but also your wallet!
And don’t forget, as you age, rates tend to decrease—at least until you hit your senior years, where they might creep up again. Contrary to younger drivers, seniors may face higher premiums due to perceived increased risk.
Average Cost of Auto Insurance in Massachusetts
Did you know the average cost of auto insurance in Massachusetts is around $1,200 per year? That’s more than the national average of $1,070. So, why are rates higher here?
The cost of auto insurance in Massachusetts can vary widely based on your specific circumstances. If you’re a young driver or own a luxury vehicle, expect to pay premium prices. But even if you’re driving a modest vehicle and have a clean record, costs can still be significant.
Breakdown of Average Auto Insurance Costs by Coverage Type
Let’s dive into the numbers. The average cost for minimum coverage is approximately $510 annually, while full coverage averages around $1,330. Here’s the deal: the more protection you want, the more you’ll pay.
| Coverage Type | Average Annual Cost |
|---|---|
| Minimum Coverage | $510 |
| Full Coverage | $1,330 |
These figures are just starting points. Your actual costs will depend on your age, driving history, and the type of vehicle you drive. But by understanding these averages, you can gauge where you stand.
Cost Comparison by Age and Vehicle Type
Age and vehicle type are major factors. Younger drivers, especially those under 25, face significantly higher premiums. Here’s a comparative view:
| Age Group | Sedan | SUV | Luxury Car |
|---|---|---|---|
| Under 25 | $2,400 | $2,600 | $3,500 |
| 25-40 | $1,200 | $1,350 | $2,100 |
| Over 40 | $900 | $1,000 | $1,800 |
As you can see, younger drivers pay significantly more, especially if they’re driving high-end vehicles. This can add up quickly.
Recent Trends in Auto Insurance Costs
In recent years, Massachusetts has seen a steady increase in auto insurance premiums. According to a recent study, rates have climbed by 15% over the past five years. The reasons? Rising repair costs and increased accident rates.
Pro Tip: Consider bundling your auto insurance with other policies or maintaining a clean driving record to lower your costs.
These trends suggest that being proactive about your insurance decisions is more important than ever. 📈 Stay informed and plan accordingly to keep your rates in check.
Discounts and Savings Opportunities for Massachusetts Drivers
Did you know that you might be leaving money on the table when it comes to your auto insurance? In Massachusetts, there are numerous opportunities to slash your premiums and put cash back in your pocket.
Here’s the deal: many insurance providers offer a variety of discounts that you may not even be aware of. By taking advantage of these, you can significantly reduce the cost of your car insurance.
Common Insurance Discounts in Massachusetts
In Massachusetts, most insurers provide a range of common discounts that can help you save. Some of the most popular include:
- Good Driver Discount: If you’ve maintained a clean driving record for a certain number of years, you could be eligible for a significant reduction in your premiums.
- Multi-Car Discount: Insuring more than one car with the same provider often results in savings.
- Safety Features Discount: Cars equipped with advanced safety features like anti-lock brakes or airbags can lower your rates.
- Good Student Discount: Students with a high GPA can earn discounts, rewarding them for their academic achievements.
Bundling Insurance Policies for Bigger Savings
Bundling is not just for phone and internet packages. In insurance, it’s a powerful way to save. When you bundle your auto insurance with home or renters insurance, providers often reward you with lower rates.
Here’s how to do it effectively:
- Contact your insurance provider and inquire about bundling options.
- Compare the bundled rate with separate policies to ensure actual savings.
- Take advantage of online tools and calculators to find the best deal.
Pro Tip: Always shop around before committing to a bundle. Different companies offer different savings, so a little research can go a long way.
Effective Tips to Reduce Auto Insurance Premiums
Want to cut down your auto insurance costs? Here are some actionable tips:
- Raise Your Deductible: A higher deductible means lower monthly premiums. Just ensure you can afford the out-of-pocket expense if needed.
- Improve Your Credit Score: Insurers often use credit scores to determine rates. A better score could mean lower premiums.
- Review Your Coverage: Periodically review your policy to ensure it matches your current needs, eliminating unnecessary coverage.
By implementing these strategies, you’ll be well on your way to potential savings on your auto insurance in Massachusetts. Remember, every little bit counts!
Choosing the Right Auto Insurance Provider in Massachusetts
Are you paying too much for auto insurance in Massachusetts? You’re not alone. With so many options out there, finding the right provider can feel overwhelming.
But here’s the deal: selecting the right insurer can save you hundreds each year. It’s all about knowing what to look for and how to compare your options effectively.
How to Evaluate and Select the Best Insurance Provider
Step #1: Check the financial stability of the insurance company. You want to ensure they’re capable of paying out claims when you need them most. Look for ratings from agencies like A.M. Best or Moody’s.
Step #2: Consider the customer service reviews. A company might be great on paper but terrible to deal with. Check reviews on websites like the Better Business Bureau or Google Reviews.
Step #3: Evaluate their coverage options. You need a provider that offers the right mix of coverage types tailored to your needs.
Pro Tip: “A lower premium can often mean higher deductibles. Always balance what you pay monthly against what you’ll pay out of pocket.”
Top-Rated Auto Insurance Providers in Massachusetts
Here are some of the top-rated auto insurance providers in Massachusetts along with their benefits:
- Liberty Mutual: Offers unique coverage options and discounts for hybrid cars.
- GEICO: Known for competitive rates and excellent customer service.
- Amica: Highly rated for customer satisfaction with great bundling options.
- Progressive: Provides a wide variety of discounts and the Name Your Price tool.
Guide to Comparing Quotes from Different Insurers
Start by gathering quotes from at least three different insurers. Use online comparison tools to save time.
Make sure to compare apples to apples. This means checking that each quote includes the same levels of coverage, deductibles, and limits.
| Provider | Annual Premium | Deductible | Additional Benefits |
|---|---|---|---|
| Liberty Mutual | $1,200 | $500 | Roadside Assistance |
| GEICO | $1,150 | $500 | Accident Forgiveness |
| Amica | $1,250 | $500 | Loyalty Discounts |
Finally, don’t just focus on the price. Take into account the overall value provided by each insurer, including customer support and additional perks.
Recent Changes and Future Trends in Massachusetts Auto Insurance
Have you ever wondered why your auto insurance premium keeps changing? Massachusetts has been a hotbed for legislative shifts that directly affect your insurance rates. Let’s dive into the recent changes and what the future holds for auto insurance in the Bay State.
The auto insurance landscape in Massachusetts is evolving. New laws and technology are reshaping how insurers calculate your premiums and what options are available to you. Stay informed to make sure you’re getting the best deal possible.
Legislative Changes Impacting Auto Insurance
In recent years, Massachusetts has enacted several legislative changes aimed at enhancing consumer protection and fairness in auto insurance. One major change is the introduction of more stringent requirements for usage-based insurance (UBI) programs. These programs use telematics to track your driving behavior, and now, more insurers are required to offer this option.
Why does this matter? Because UBI can significantly lower your rates if you’re a safe driver. BUT, it also raises privacy concerns, as it involves sharing your driving data with insurers. The state has responded by implementing strict data protection laws to ensure your information stays secure.
Emerging Trends in Auto Insurance Offerings
Here’s the deal: the insurance industry in Massachusetts is ripe for innovation. More companies are offering customized policies that cater to specific driver needs, like pay-per-mile insurance and policies for electric vehicles. This is great news for those who drive less or have eco-friendly cars.
One trend that’s gaining traction is the use of AI and machine learning to assess risk and streamline claims processing. This tech not only speeds up the claim process but also helps insurers offer more competitive rates. Expect to see more insurers adopting AI in the coming years.
Technology’s Impact on Future Auto Insurance
Technology is not just a trend; it’s a game-changer. The rise of autonomous vehicles is set to revolutionize the auto insurance industry. As self-driving cars become more common, insurers will need to rethink their models, focusing more on product liability than personal liability.
Another tech development to watch is the integration of smartphone apps that offer real-time feedback on your driving habits. These apps can help you become a safer driver, potentially reducing your premiums. Pro Tip: Download a reputable driving app to start saving on your insurance right away.
In summary, staying abreast of these changes and trends will not only keep you informed but could also save you money. The future of auto insurance in Massachusetts looks promising, especially with technology paving the way for more personalized and efficient offerings.
Last Word
Wrapping it up, navigating the world of auto insurance in Massachusetts doesn’t have to be a daunting task. With the right knowledge, you can easily find a plan that not only meets legal requirements but also fits your budget and lifestyle. Stay informed, compare wisely, and you’ll be well on your way to securing the best possible coverage. Drive safe and happy hunting!
FAQ
What are the minimum auto insurance requirements in Massachusetts?
In Massachusetts, drivers are required to have minimum liability coverage of $20,000 per person and $40,000 per accident for bodily injury, along with $5,000 for property damage.
What factors influence auto insurance rates in Massachusetts?
Insurance rates in Massachusetts are influenced by factors such as the driver’s age, driving history, type of vehicle, location, and coverage options chosen.
How do different regions in Massachusetts affect insurance costs?
Insurance costs can vary significantly depending on the zip code and region due to factors like crime rates, traffic congestion, and accident statistics.
Are there discounts available for Massachusetts drivers?
Yes, many providers offer discounts for Massachusetts drivers such as safe driver discounts, multi-policy discounts, and discounts for safety features.
How can technology impact the future of auto insurance in Massachusetts?
Technology is likely to bring changes such as telematics, which monitor driving habits and can lead to personalized insurance rates, potentially lowering costs for safe drivers.
